Long-term expat health insurance: choosing the best international cover
As soon as you settle abroad long term, your social security entitlements end. Without robust cover, an emergency can cost more than $50,000 in the United States. careXpat, a certified insurance brokerage, finds the right protection for you.
More than travel insurance: your new social security cover
Settling outside France means adapting to a new healthcare system. Expat insurance ensures fast access to private healthcare, where public services are often overstretched, and protects you against everyday unexpected events as well as life-threatening emergencies.
Unlike a standard travel policy, it fully replaces French social security and provides your primary protection over the long term.
First-euro cover, CFE, obligations: the essentials
First-euro insurance
The simplest and most popular solution: a private insurer reimburses you from the first euro spent, without contributions to a French public scheme. Centralised administration, fast reimbursements and high limits.
- A single contact for all your reimbursements
- Ideal for the USA and Asia, where private healthcare is essential
- Very high benefit limits
First-euro insurance or CFE plus top-up cover?
First-euro insurance
- How it works
- A private insurer reimburses you from the first euro.
- Advantages
- Centralised administration, high limits and fast reimbursements.
- Ideal for
- USA, Asia: essential, direct access to private healthcare.
CFE plus top-up cover
- How it works
- Contributions to French social security plus private health insurance.
- Advantages
- Continuity of entitlements and an easier return home.
- Ideal for
- Chronic conditions and frequent trips back to France.
What your policy should protect
Medical expenses and hospitalisation
The core of your policy: hospitalisation, surgery and emergencies covered without overwhelming out-of-pocket costs, in line with healthcare prices in your host country.
Routine care
GPs, specialists, medication, laboratory tests and radiology.
Medical repatriation
Medically assisted return to France or the nearest suitable hospital.
Hospital network and worldwide direct billing
An extensive partner network and direct payment of hospital costs, so you do not have to pay large sums upfront.
Maternity cover without a waiting period
Optional immediate maternity cover, depending on the policy.
Dental and optical
Optional benefits to tailor your cover to your needs.
Which expatriate profile fits you?
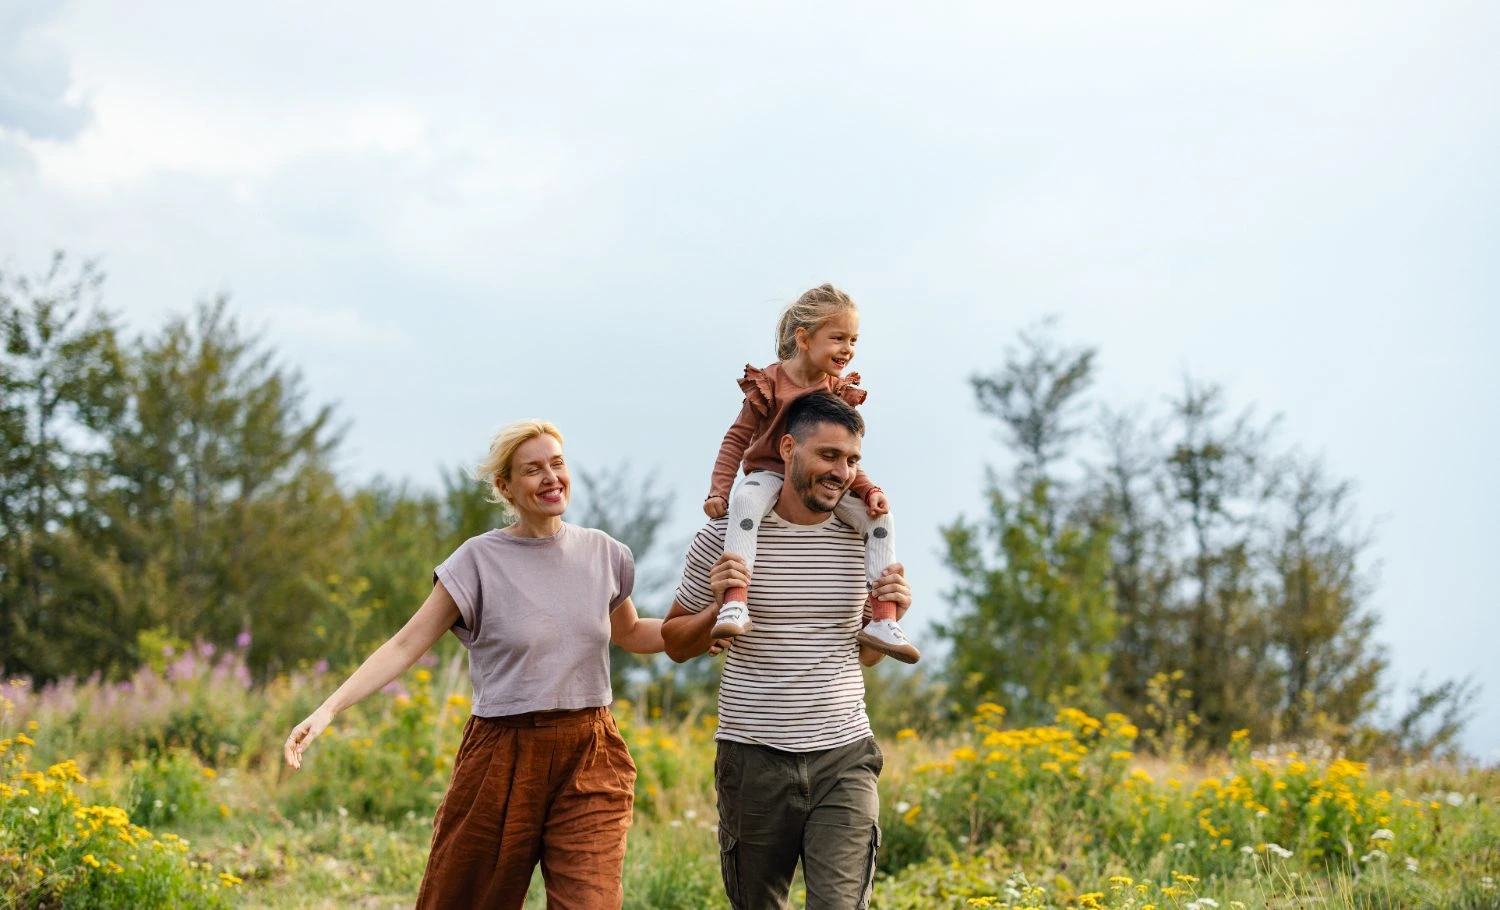
The expatriate family
Maternity, paediatric follow-up and orthodontics: benefits designed to protect your spouse and children, wherever you live.
The retiree
High hospitalisation limits, chronic conditions and reliable repatriation.
Freelancer · nomad
Flexible multi-country cover for those who change destinations several times a year.
Long-stay student
Comprehensive yet affordable cover for a course lasting more than a year.
5 criteria for choosing the right plan
Annual limits
The maximum amount reimbursed each year, suited to local costs.
Network and direct billing
The reach of the partner hospital network to avoid upfront payments.
Waiting periods
The time before certain benefits become effective.
Pre-existing conditions
How the insurer handles your medical history.
French-language assistance
A responsive service in French, available wherever you are.
Ready to protect your move abroad?
Our team of experts works with you to provide personalised support, from choosing a policy to taking out cover, so you can settle abroad with peace of mind.